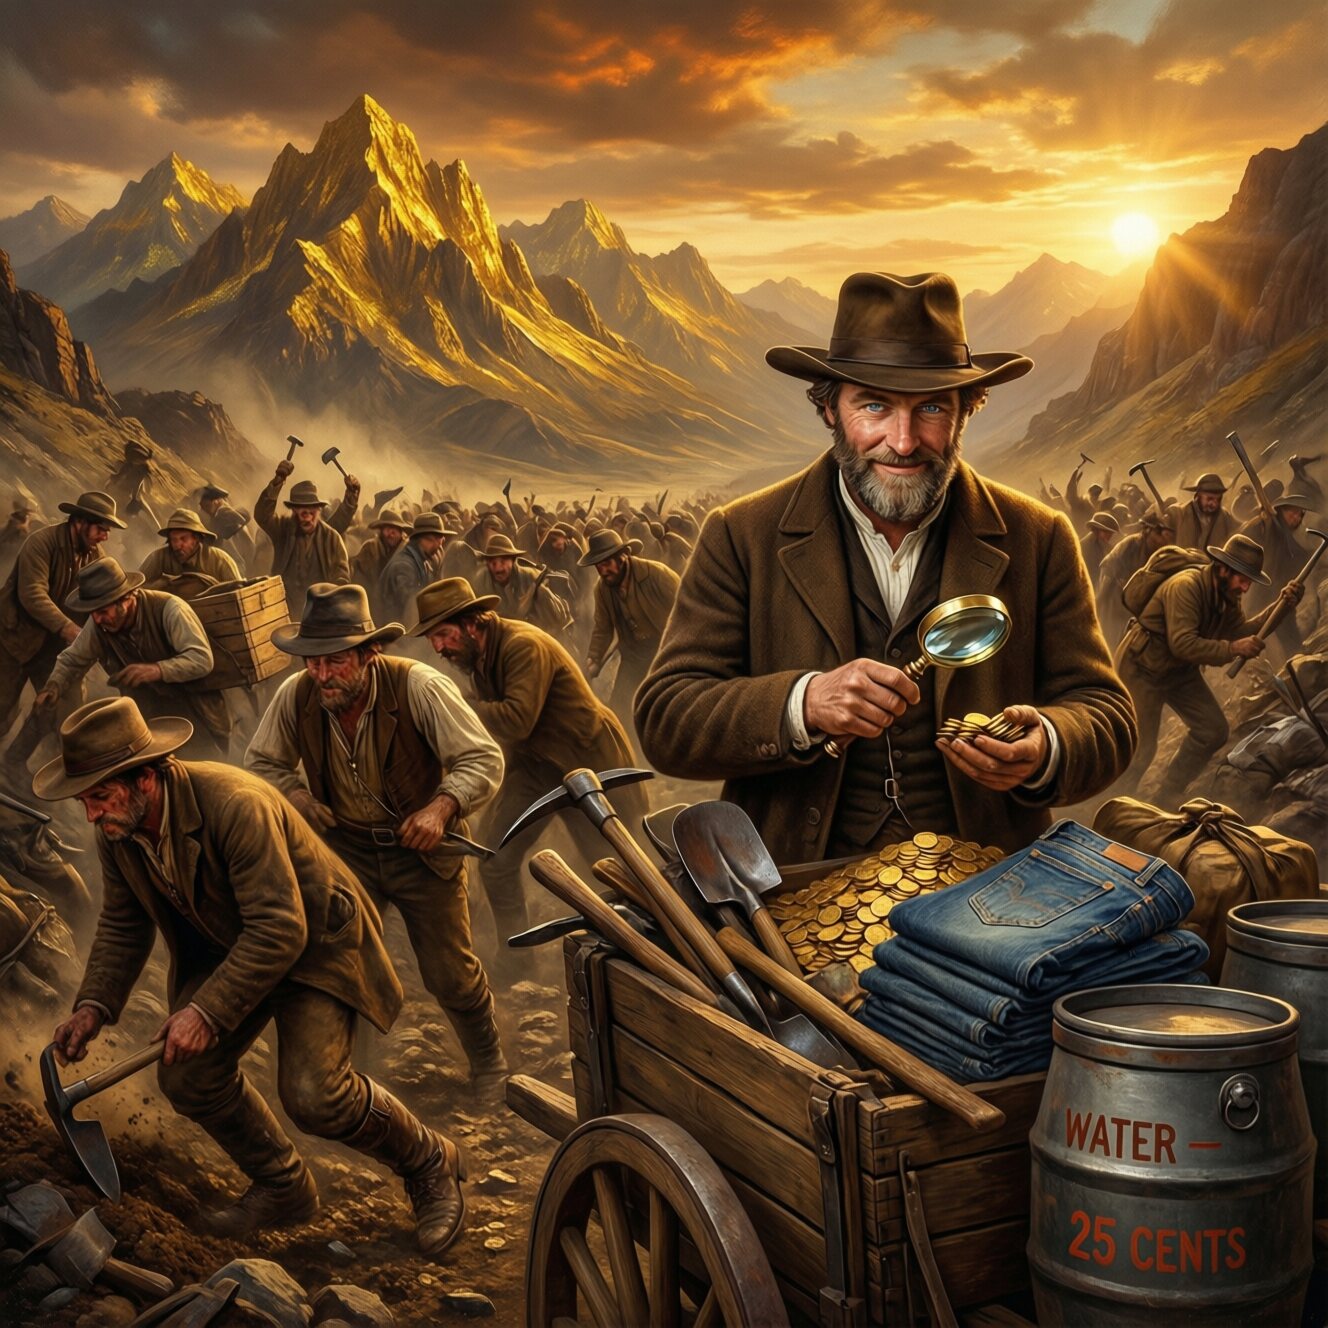
The 19th-century gold rushes in America and Australia: countless people rushed madly to the gold mines hoping to strike it rich overnight, but the vast majority came away with nothing; meanwhile the merchants selling shovels, picks, jeans, drinking water, and other mining tools and supplies steadily made a fortune—the most typical being the founder of Levi’s jeans, and the merchants who sold tools to miners at high prices.
Open social media and Hangzhou’s OPC (one-person company) propaganda is everywhere: “Open a company from a single desk,” “AI + an individual = a million yuan a year,” “Low-cost entrepreneurship, government subsidies to back you up.” It seems that as long as you register an OPC, you can easily escape unemployment, achieve freedom over your time, and become a beneficiary of the era. But the truth is far crueler than the propaganda—Hangzhou’s hard push for OPC was never to let ordinary people “earn while lying down,” but a precise urban-governance measure to hedge against office-vacancy and employment pressure, and most ordinary people who blindly enter the game are merely the “fuel” harvested in this arrangement; the so-called entrepreneurial dividend is nothing but sugar-coating wrapped around a trap. A friend I know said that at EFC you can rent five or six workstations for 2,500, cheaper than even an address-affiliation service.
First, let’s clarify a core fact: the underlying logic of Hangzhou’s frantic push for OPC was never “entrepreneurship for all,” but “buffering for all.” Every favorable policy we see is in essence about solving the city’s two big problems and has nothing to do with ordinary people’s “startup success.” Every key figure has an authoritative source and is by no means fabricated.
One: The “Cure” for High Office Vacancy Rates Is Not Your Entrepreneurial Opportunity
Many people are moved by “government support, low-cost workstations,” unaware that the core purpose of these benefits is to revitalize Hangzhou’s backlog of office inventory. In recent years Hangzhou’s office vacancy rate has kept soaring, long since breaking past the industry’s warning line, becoming a “burden” on urban development.
According to a Cushman & Wakefield report, in the second quarter of 2025 Hangzhou’s Grade-A office vacancy rate reached 26.7%, far above the 20% industry warning line, surging 8 percentage points in just four years. By 2026 the figure worsened further: according to CRIC data, Hangzhou’s Grade-A office vacancy rate had climbed to 24.5%–28.6%, with the Wulin business district reaching as high as 36.8%, Qianjiang New City at 26.2%, and non-core areas (Chengdong, Linping, Chengbei) exceeding 35%, with some secondary business districts approaching 40%.
At the same time, office supply keeps flooding in: as of the fourth quarter of 2025, Hangzhou’s Grade-A office stock had reached 7.4286 million square meters, with over 600,000 square meters of new supply concentrated on the market in 2026, while the leasing demand of traditional large and small enterprises keeps shrinking, and the internet giants are cancelling leases and shrinking office space one after another, leaving a large amount of office space vacant for the long term. Rents have kept diving as well: in the first quarter of 2026 Hangzhou’s average total office rent was 21,829 yuan/month, a drop of about 34.66% compared with 33,406 yuan/month in 2024; rents in some non-core areas nearly halved, and even with price cuts and rent-free periods it is still hard to move the space.
Against this backdrop, OPC became the “optimal solution” for Hangzhou to revitalize its offices. Policy support for “multiple licenses at one address” and “workstation registration,” allowing “a company from a single desk,” is in essence about splitting the idle space of hundreds or thousands of square meters in vacant offices into mini-workstations and independent office rooms, repackaged under the name of “startup parks,” and letting ordinary people rent these once-ignored workstations. To you it looks like “low-cost entrepreneurship,” but in fact you’re helping the government and office operators liquidate inventory—every workstation rent you pay is “footing the bill” for Hangzhou’s commercial-real-estate crisis, not “investing” in your own entrepreneurial dream.
Two: The Cushion of the “Entrepreneurship Narrative” Hides the Helplessness and Traps of the Unemployed
Hangzhou’s other core purpose in pushing OPC is to dissolve the structural unemployment pressure brought by the wave of internet layoffs, using the narrative of “going it alone” to achieve a soft landing in the unemployment data. According to the Hangzhou government work report, Hangzhou’s official 2026 goal is over 250,000 new urban jobs and an urban surveyed unemployment rate kept under 5%, but the real employment contradiction is extremely sharp.
Zhaopin’s “2026 Spring Survey Report on Workplace Job-Hopping” shows that 33.3% of surveyed workers believe “one-person companies will definitely become more and more common,” and 20.8% believe “more employees will use AI to quit and go it alone.” But behind this seemingly optimistic data is a severe employment predicament: in the 2026 spring hiring season Hangzhou received 18.3 résumés per job on average, the youth unemployment rate for ages 16-24 reached 19.6%, the internet giants kept shedding staff, and the unemployment wave of 35+ workplace workers stacked on top, leaving a large workforce idle while traditional enterprises can no longer absorb the huge employment gap.
Thus OPC became a “decent cushion”: a person unemployed at home counts as a registered unemployed person and puts pressure on the employment assessment; but as soon as he registers an OPC, he becomes a “self-employed entrepreneur,” not only not counting as unemployed but also counting toward the “new market entities” and “new urban jobs” data, perfectly achieving a soft landing for the data. Hangzhou’s one-time OPC startup subsidy (up to 10,000 yuan) and social-security subsidy (500-800 yuan per month for up to 3 years) look like support for entrepreneurs, but in fact use a small amount of fiscal money to leverage the unemployed into bearing the cost of employment themselves—more efficient than directly handing out unemployment benefits or setting up public-welfare posts.
But for ordinary people, behind this “decency” is an unbearable risk. According to an April 2026 insight report from Hangzhou News Center, among current Hangzhou OPC entrepreneurs, 52.4% of respondents are still in the product-validation stage with monthly income under 7,000 yuan; only 37.1% have entered a sustainable-operating range, and those with monthly income over 600,000 yuan account for just 10.5%. More cruelly, a field visit by Sina Finance in April 2026 to OPC communities in four cities—Beijing, Shanghai, Suzhou, and Hangzhou—found that of the 12 Hangzhou OPC companies visited, 4 had shut down (33%), 3 were half-stalled (25%), and only 1 had run a profit, while the community’s workstation vacancy rate reached 30%.
Those unemployed people moved by the “individual CEO” narrative who blindly register an OPC are mostly just “unemployed with a new identity”—no orders, no income, yet having to bear the cost of registration, bookkeeping, and tax filing, and facing the second blow of “startup failure.” The so-called “cushion” finally becomes a “trap.”
Three: The Exaggerated AI Dividend Hides Multiple Harvesting Schemes
In Hangzhou’s OPC propaganda, the most attractive line is “AI + an individual = startup success,” claiming that AI tools can let one person do a whole team’s work and lower the threshold of entrepreneurship. But the truth is that the AI dividend is severely exaggerated, and behind it lurk the multiple harvests of AI vendors, training institutions, and financial-and-tax service providers.
First, the actual limits of AI tools far exceed the propaganda. According to industry insiders, current mainstream AI Agent tools (such as OpenClaw and WorkBuddy) are not stable enough, often throwing execution errors, and their automated workflows are far from the “smooth” advertised; they also require a certain technical debugging ability to use proficiently, so even if ordinary people get a free AI model account, it’s hard to quickly raise productivity. More importantly, the compute cost of AI tools is severely underestimated: as AI providers cancel free quotas, token consumption becomes an ongoing fixed expense, and the token consumption of complex tasks far exceeds expectations—another extra burden for ordinary people.
More hidden is that a large number of training institutions exploit the OPC and AI-startup frenzy to harvest anxiety madly. A Xinhua Finance investigation found that some training institutions’ OPC startup courses over-hype the “money prospects” and deliberately avoid the risks, packaging them with phrases like “college students, just jump in” and “a million a year,” pricing arbitrarily and with “mentor” qualifications opaque; many so-called “startup mentors” list only an English name and a vague job description, with no way to verify their real résumés.
These courses are mostly “not worthy of the name”: for a networking event charging 168 yuan, there is almost no substance in 3-4 hours—more output of “emotional value”—and when entrepreneurs raise practical questions such as “how to acquire customers” and “how to monetize,” the response is a perfunctory “keep the right mindset” and “perseverance matters most.” Some institutions also plant a 999-yuan annual-membership card and 10,000-yuan one-on-one coaching courses; amid “hard-sell” tactics many entrepreneurs pay blindly, only to find afterward that the course content is seriously inconsistent with the ads and that seeking redress is difficult. More ironically, the supposed foreign “benchmark of an OPC earning 5 million dollars a year” actually makes its money by “teaching others to do OPC,” and its claimed profit margin has no public audit to back it up—it has no reference value at all.
Beyond this, OPC also hides compliance risks. Under the Company Law, if a shareholder of a one-person limited liability company cannot prove that the company’s property is independent of his own, he must bear joint liability for the company’s debts. Many ordinary people, after registering an OPC, are used to mixing personal and company accounts, and once a debt problem arises, the individual must fully cover it. At the same time, an OPC must pay corporate income tax plus personal income tax, with complex financial accounting, and taking company funds into a personal account may trigger a finding of tax evasion—for ordinary people lacking financial-and-tax knowledge, it’s easy to step on a landmine.
Four: Be Clear-Headed: OPC Is a Tool, Not a “Startup Shortcut” for Ordinary People
We don’t deny the value of OPC—it can indeed provide a compliant vehicle for “super-individuals” with core ability and resources, offer a transitional buffer for the unemployed, and help Hangzhou resolve its two big problems in urban development. But we must see clearly: in the chain of Hangzhou’s push for OPC, every party benefits, and it is precisely the ordinary person who easily becomes the “sacrifice.”
The government uses OPC to complete its employment assessment, dissolve real-estate risk, and seize the AI-industry stronghold; office operators revitalize idle assets and reconstruct their profit model, with per-square-meter efficiency multiplied 3-5 times; AI vendors, training institutions, and financial-and-tax service providers find new customer groups and become the sure-profit “water sellers.” But the ordinary person, without core skills, without stable orders, without business experience, who blindly enters the OPC game will most likely end up renting cheap workstations, buying expensive courses, and burning time costs, and finally either deregistering the company or becoming an “empty-shell entrepreneur”—making no money and possibly taking on debt.
Liu Yuhan, founder of Hangzhou Yinxun Education, stated clearly that the OPC success rate is under 20%, and may end up not even reaching that; many novices who enter blindly shut down their companies within 3-4 months due to monetization difficulties and exhausted funds. Huang Yangzhi, founder of Yingling Zhitu, also warns that AI can only lower the technical execution threshold and cannot make up for the entrepreneur’s lack of business ability; if you pin your hopes on startup courses and others’ experience, you’ll most likely be disappointed.
Finally, a reminder to all ordinary people moved by OPC propaganda:
Don’t mistake “policy benefits” for “entrepreneurial dividends”: the government’s subsidies and low-cost workstations are in essence about liquidating inventory and buffering unemployment, not letting you “earn while lying down.” Before registering, first think clearly whether you have monetizable core skills.
Don’t be fooled by the “AI myth”: AI is an auxiliary tool, not a “startup magic weapon”; without business thinking and without customer-acquisition ability, no AI however powerful can make you profitable.
Don’t blindly follow the crowd into registering: if you just want a side hustle, there’s no need to rush into registering an OPC—first get a monetization loop running as an individual, and only consider formalization once your monthly income is stable and you have a long-term plan. If you’ve already registered, be sure to separate personal and company accounts to avoid compliance risk.
Be wary of paid training and communities: any OPC course that exaggerates returns, avoids risks, and hard-sells you must be avoided. Real entrepreneurial substance never makes money by “getting harvested.”
Hangzhou’s push for OPC is itself blameless, but we must see the logic behind it: this is not a carnival of entrepreneurship for all, but an urban-governance action where multiple interests collude. For ordinary people, using the policy dividend to lower your own costs and improve your ability is a good thing, but blindly believing “OPC = startup success” will only get you fooled and harvested.
Entrepreneurship has never had a shortcut, and OPC is no exception. Seeing the trap clearly, holding fast to your own heart, and using the rules rather than being swept along by them—that’s what an ordinary person should do most. After all, what lets you stand firm was never the identity of a “one-person company,” but your own core ability.
Ordinary People Facing Unemployment Must Be Careful Not to Be Harvested
To put it bluntly, the essence of loud propaganda was never “giving ordinary people an opportunity” but “finding ordinary people to take over the bag.”
Whether it’s the 19th-century American gold rush, when the promotional cries of “go west and strike it rich overnight” blanketed the land, or today’s “OPC one-person company, a million a year” hyped across the internet, the people shouting slogans into the megaphone are all people who have already secured the “shovel-selling” position. They hype the opportunity as having zero threshold and being within everyone’s reach not to share the cake with you, but to get you onto the field—to pay them workstation rent, buy high-priced startup courses, stock up on paid AI tools, and take over the unsellable idle assets in their hands, becoming the bag-holder for their cash flow and risk.
An even more painful truth is: the opportunities that can truly let ordinary people turn their lives around are always quietly made rich, and would never get loud propaganda.
The real dividend period is entirely held up by the information gap and the threshold gap; the people who eat the dividend first only quietly scale up and lock in profits, wishing the whole world knew nothing. By the time this opportunity starts flashing across the whole internet and even the auntie at the convenience store downstairs can chat with you about it, the real dividend period is long over, and what’s left is all fabricated pits, just waiting for ordinary people to step in and fill the holes.
These heavily packaged “opportunities for all” are in essence a placebo for the emotions, plus a risk-transfer device, custom-made for ordinary people. Take buying a house: the most cunning part of this scam is that it builds an illusion for ordinary people: “You buy the house, and you can also sell it to the next person at a higher price—you too are a player in this wealth-creation game.” But the truth is, from the very moment the promotional hype begins, you’ve never been treated as a “fellow player,” but as the final bearer of risk and provider of liquidity.
The speculators who amassed a large number of properties at extremely low cost early on and are waiting to cash out and exit; the developers with high inventory who need to collect payment and repay debt; the agents who earn commissions from transactions; and even the entities tied to land finance that need to revitalize the land market. They hold the goods, and all their paper wealth is illusory; there must be ordinary people to step in and take over before they can dump the houses and the debt and turn paper wealth into real money, pocketing it safely.
And the pie they drew for you of “continuing to sell at a high price” could never be delivered from the very start.
The people who can truly make money from flipping houses always complete their positioning before the market starts moving, buying at the land-price stage and the bottom of the early market launch. By the time the whole internet starts frantically advertising the wealth-creation myth and even the auntie at the vegetable market can chat with you about “buying a house to hedge inflation,” it’s already the final stage of their selling off. They have long devoured every bit of this round’s price-rise profit; the price at which you take over is already the peak of this round’s market.
After you take over, you’ll discover that the rules of the game have completely changed: the down payment you scraped together from six wallets and the 30-year mortgage you took on directly let the people upstream cash out and exit; and you’ve taken on all the risk—if housing prices go sideways, the interest you lose each year is hundreds of thousands; if prices fall, you first lose your entire down payment and still have to keep paying the bank; if you want to resell at a high price, you find the market has long lost liquidity, and there’s simply no next person willing to take over.
评论
0 条评论